Credit Genie

Screenshots
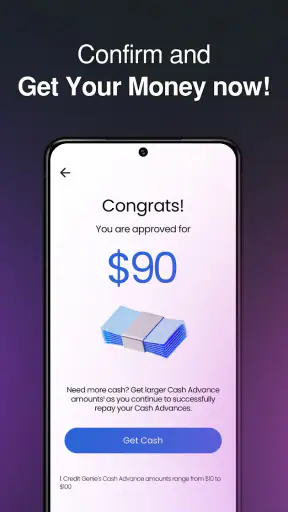
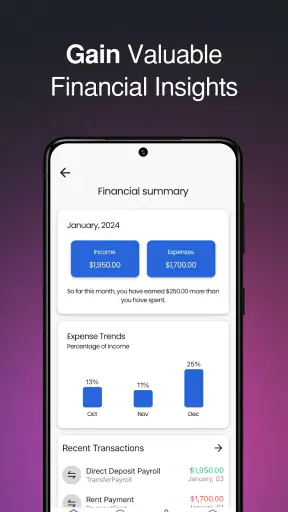
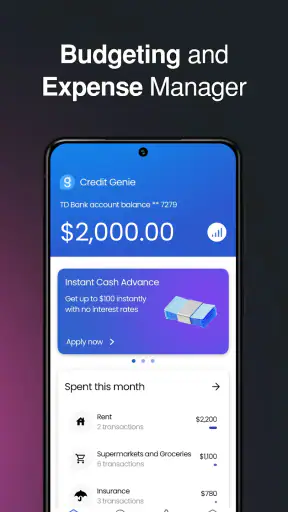
Details
- Rating
- 9.66K reviews
- Version
- 3.5.0
- Developer
- Creditly Corp
Analysis by Norviv
I approached Credit Genie as a practical finance app rather than a flashy money tool. Its promise is broad, but the real question is simpler: can it help me move through everyday credit and money tasks without adding confusion? My experience is that it can be useful when I treat it as a focused part of my financial routine, not as a replacement for every banking, budgeting, or credit service I already use.
Developed by Creditly Corp, the app is free and aimed at an Everyone audience. It has built a strong public reception, with a 4.7 average from around 83 thousand ratings and more than a million installs. Those figures suggest that many people find the basic experience worthwhile, but they do not remove the need to check details carefully before acting on any financial information.
Where the first experience can become confusing
The most common difficulty with a broad finance app is knowing what to do first. A money app can appear simple on the opening screen while still asking the user to make decisions about identity, accounts, credit information, notifications, or personal preferences. When several choices appear at once, I recommend resisting the urge to tap through everything quickly. Read each screen and decide whether the requested step is necessary for the task you actually want to complete.
That approach matters especially with Credit Genie because the app sits in the credit and personal-finance space, where a small misunderstanding can have more impact than a missed setting in a social app. I would begin with one clear goal, such as reviewing the information available to me or understanding which part of the service I want to use. Starting with a narrow purpose makes it easier to notice whether the app is helping or whether I am simply creating another place to monitor.
Another point of friction is expectation. The short store description calls it “Credit Genie,” while the broader summary presents it as an all-in-one money app. I would not interpret that as a promise that it replaces a bank, a credit bureau, a budgeting spreadsheet, and every financial product in one place. The useful interpretation is that it brings credit-related tools into a single mobile experience. That distinction keeps the first session realistic.
If a screen appears empty, incomplete, or slower than expected, I would not immediately assume that the app has lost information. Finance services often depend on a successful connection, a completed profile, or information becoming available from another system. I would first check whether the setup process finished, whether the device is online, and whether I am signed into the intended account. These are simple checks, but they prevent unnecessary resets.
Start with a small, controlled setup
My preferred setup method is to install the current release, version 3.5.0, open it on a stable connection, and move through the initial screens without multitasking. If the phone is running an older operating system, compatibility may become a practical concern because the app requires at least version 10. Updating the phone is not always the right first move, though; I would also make sure there is enough storage and that the device is not aggressively restricting background activity.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would keep the first session short. Complete the essential account steps, look around the main areas, and then close and reopen the app. This gives me a quick way to tell whether the basic sign-in state is being retained. It also separates setup friction from later workflow problems. If the app works after reopening, the original issue may have been a temporary connection or a one-time loading delay rather than a damaged installation.
Before connecting anything financial, I would make sure I am using the correct personal account and a private network. I would avoid public Wi-Fi for sensitive work and would not share one-time codes or login details with anyone claiming to provide support. These are not special requirements of one particular app; they are sensible habits for any service dealing with money and credit.
Notifications deserve a deliberate choice. I prefer to allow only alerts that help me act, review, or notice an important change. If the app requests several notification types, I would consider which ones I will actually read. Too many alerts can make a financial tool feel urgent all the time, encouraging rushed decisions. A quieter setup is often more useful than enabling everything during installation.
What to check before deciding that something is broken
When information does not appear, I work through the problem in a fixed order. First, I confirm that the app is updated and that the phone meets the minimum operating-system requirement. Next, I test the connection by switching between a reliable Wi-Fi network and mobile data, if available. Then I force-close and reopen the app, sign out only if I can confidently sign back in, and check whether the same issue occurs after a fresh launch.
I avoid clearing app storage as an early troubleshooting step. That can remove local session details and turn a small display problem into a full sign-in problem. Reinstalling can have the same drawback. I would reserve those actions for a situation where the normal restart and connection checks fail, and only after confirming that I know the credentials and recovery method needed to return to the account.
A useful habit is to note exactly what happened. “It does not work” is difficult to diagnose, while “the screen loads but the next action does nothing” gives a much clearer starting point. I would record the section I was using, the action I tapped, whether an error appeared, and whether the problem remained after reopening. That information is also more useful if I need to contact support.
I would not repeatedly submit the same action just because the screen looks slow. In a financial context, duplicate attempts can create uncertainty about whether a request was accepted. Wait for the screen to settle, look for a confirmation, and check the relevant activity area before trying again. If the status is unclear, stopping is safer than tapping several more times.
Recovering a money workflow without making it messier
Credit Genie is most useful to me when I use it as a review point in a larger routine. For example, I might open it during a weekly money check, review what needs attention, make a note of anything unclear, and then use the appropriate official service for a final account decision or transaction. This keeps the app from becoming the only place where I verify important information.
A practical everyday scenario would be preparing for a major purchase. I would open the app to review my current credit-related picture, compare what I see with my own recent records, and think about whether the purchase fits my budget. I would not treat a single screen as an automatic approval, guarantee, or complete financial assessment. The value is in organizing my attention before I make a decision, not in letting the app make the decision for me.
One non-obvious advantage of this approach is that it exposes mismatches early. If the information in the app does not line up with paperwork, a lender’s account, or another trusted source, I would pause and identify which source is current and relevant. That pause is more valuable than immediately refreshing the same screen. It turns the app into a prompt for verification rather than a source of rushed conclusions.
Another useful workflow is to separate monitoring from action. I can use Credit Genie to understand what deserves attention, but I would avoid treating every notification or change as a reason to apply for something, move money, or alter a payment plan. This is where the app requires judgment. A convenient interface can make financial actions feel easier than they really are.
If a session fails halfway through, I would restart from the last confirmed point instead of repeating the entire process blindly. Check whether the app shows a completed status, confirmation, or updated screen. If it does not, use the relevant account or service to verify the result before trying again. This recovery method is slower than repeatedly tapping, but it reduces the chance of creating duplicate requests or misunderstanding an incomplete action.
Where it fits beside familiar alternatives
Compared with a traditional banking app, Credit Genie is better suited to credit-focused awareness than to being the main place for day-to-day banking. A bank app remains the natural choice for checking balances, moving money, and reviewing transactions tied directly to a bank account. I would use Credit Genie alongside that app when I want a separate view of credit-related matters rather than expecting one tool to cover both roles equally well.
Compared with a spreadsheet, the app is more convenient for quick checks on a phone. A spreadsheet, however, gives me more control over categories, custom calculations, long-term records, and personal assumptions. Someone who enjoys building a detailed budget may find a spreadsheet more transparent. Someone who wants a ready-made mobile checkpoint may prefer Credit Genie, provided they are comfortable with a less customizable workflow.
Compared with a dedicated credit-monitoring service, the trade-off is breadth versus specialization. Credit Genie’s appeal is the attempt to bring several money-related tasks into one accessible app. A specialized service may be a better choice for a user who wants the deepest possible focus on one narrow aspect of credit information. I would choose based on the job: convenience for regular awareness, or specialization when a single detail needs unusually close attention.
The free price makes experimentation easier, but free does not mean consequence-free. My time, attention, and financial decisions still matter. I would judge the app by whether it reduces confusion during my routine, not simply by whether I can install it without paying. If I find myself checking several tools because the information is unclear, the convenience advantage may disappear.
When the problem is outside the app
Not every missing update, rejected action, or unexpected result originates in Credit Genie. A connected financial service may be unavailable, a provider may be processing information, or the underlying record may not yet reflect a recent change. The app can display what it receives, but it cannot make every external system update immediately.
This is why I compare important information with the source that actually controls the account or decision. If a lender, bank, or other official service shows a different status, I give that source priority for action and use the app as a secondary reference until the difference is understood. I would also avoid assuming that a delayed display means a negative change.
Device conditions can create misleading symptoms too. Low storage, an outdated system, unstable connectivity, battery-saving restrictions, or an interrupted update can all make an app seem unreliable. A clean restart, a stable connection, and a completed update are reasonable first steps. If other apps are failing in the same way, the issue is probably broader than Credit Genie.
Privacy and security concerns should also be handled carefully. I would use the official app-store route, keep the phone protected, and be suspicious of messages asking for credentials or codes. If something looks inconsistent, I would verify it through a trusted official channel rather than following an unexpected link or relying on a screenshot. The app can support a safer routine, but it cannot replace basic account security.
Who should use it, and who should skip it
I think Credit Genie is a good fit for someone who wants a straightforward mobile place to review credit and money information, especially if opening several separate services feels tiring. It may also suit a person who is beginning to pay closer attention to credit and wants a regular check-in habit without building a complex financial system from scratch.
I would be more cautious recommending it to someone who needs detailed budgeting, advanced customization, or a complete banking replacement. A person who already has a trusted system that clearly covers the same tasks may gain little from adding another app. Likewise, anyone who tends to act immediately on alerts should use a slower review process, because financial convenience is not the same as financial advice.
The Everyone age rating makes the app broadly accessible, but age suitability does not mean every financial decision is simple. Younger users or anyone new to credit should take time to understand what each screen means and discuss significant decisions with a trusted, qualified person. The app can organize information; it should not be treated as permission to borrow or spend beyond a realistic plan.
My practical verdict after using its approach
Credit Genie works best when I give it a defined role: a convenient credit and money checkpoint that helps me notice what deserves attention. Its free access, broad purpose, and large user base make it easy to try, while the current version gives users a clear starting point on supported devices. I appreciate the convenience, but I would keep official account sources, personal records, and careful judgment in the loop.
The main limitation is not necessarily a missing button or a difficult screen. It is the risk of expecting an all-in-one money app to remove the need for verification. When setup stalls, I check the operating system, connection, session, and update before reinstalling. When information looks wrong, I compare it with the controlling financial source. When an action is unclear, I stop rather than repeat it.
My recommendation is to try Credit Genie if you want a simple, mobile-first way to keep credit-related tasks in view, but use it as part of a wider financial routine. For me, that balance delivers the most value: the app reduces the effort of checking, while the final responsibility for interpreting information and making money decisions stays with me.
Frequently Asked Questions
01What is Credit Genie, and how does it work?
Credit Genie is a personal finance app designed to help users monitor and manage aspects of their financial life, such as credit information, spending, and available cash-flow tools. After creating an account, you may be asked to provide personal and financial details so the app can personalize its features. Available services can vary by location, eligibility, and the version of the app.
02Is Credit Genie a loan app, and can it guarantee approval?
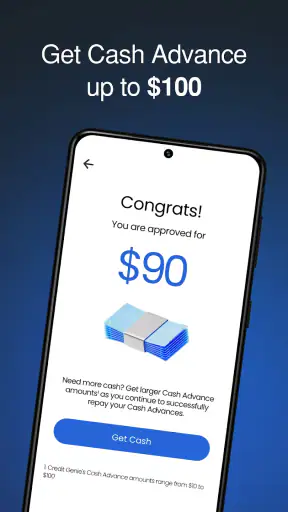
Credit Genie may provide access to financial products or cash-advance-related services, depending on your eligibility and where you live, but it should not be treated as a guaranteed loan provider. Approval, limits, fees, repayment terms, and availability can differ between users. Always review the full agreement carefully before accepting any offer, and never assume that using the app will automatically improve your credit score.
03Does Credit Genie affect my credit score?
Using Credit Genie does not necessarily affect your credit score in the same way as applying for traditional credit. Some features may use a soft inquiry, while a financial product or credit application could involve additional checks or reporting. Because practices may change according to the service offered, read the app’s disclosures and privacy information to understand whether an inquiry or account activity may be reported.
04What information does Credit Genie require, and is it safe to use?
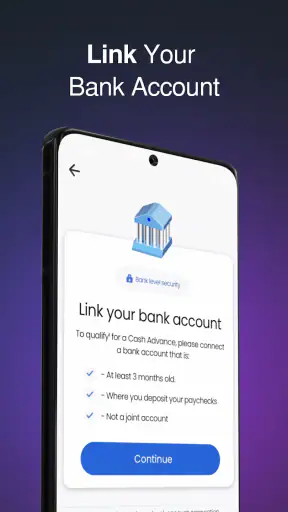
Credit Genie may request information such as your name, contact details, income, employment information, bank account details, or identification data to verify your identity and provide certain features. Before signing up, check the app’s privacy policy, permissions, security statements, and developer information. Use a strong password, avoid sharing verification codes, and download the application only from an official app store.
05Are there fees, repayment requirements, or subscription costs in Credit Genie?
Some Credit Genie features may be free, while other services can involve fees, optional subscriptions, expedited-transfer charges, or repayment obligations. The exact cost depends on the product you use, your eligibility, and your location. Before confirming anything, examine the fee schedule, due dates, cancellation rules, and automatic-payment terms. Missing a repayment or misunderstanding a charge could create additional financial problems.


